If you’re retired or approaching retirement with a meaningful portfolio of shares, managed funds, term deposits or other private investments, changes to two key age pension thresholds from 1 July 2026 may be worth your attention, particularly if you were told in the past that your assets or income put you just outside the pension system altogether.
What’s Changed
The assets test thresholds have increased from 1 July 2026, including both the upper cut-off limits and the asset-free areas that determine when the age pension starts to reduce.
The upper limits, the point at which pension entitlement cuts out completely, have increased as follows:
Assets Test Cut-off: Non-homeowners
- Single: $1,000,500 (up from $980,000)
- Couple (combined): $1,369,500 (up from $1,343,000)
Assets Test Cut-off: Homeowners
- Single: $733,500 (up from $722,000)
- Couple (combined): $1,102,500 (up from $1,085,000)
The asset test for homeowners excludes the value of primary place of residence.
Income and Deeming Changes
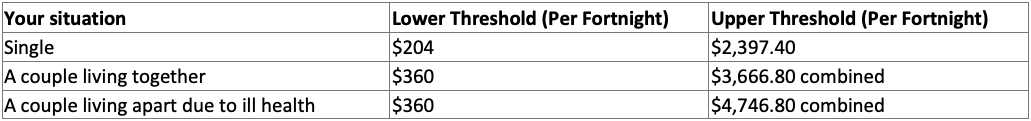
Centrelink’s deeming rules assume your financial investments earn a certain rate of income, regardless of what they actually return. From 1 July 2026, the threshold at which the higher deeming rate of 3.25 per cent applies has increased to $66,800 for singles (up from $64,200) and $110,600 for couples (up from $106,200). The fortnightly income-free area has also risen, to $226 for singles (up from $218) and $396 for couples (up from $380).
Income Test Cut-off (Per Fortnight)
- Single: $2,627.80 (up from $2,619.80)
- Couple (combined): $4,016.80 (up from $4,000.80)
Why This Could Matter To You
If you’ve built a significant portfolio of assessable private investments, direct shares, managed accounts, term deposits and similar holdings, there’s a good chance you’ve previously been assessed as ineligible for any age pension because your assets or deemed income sat just above the cut-off. With these thresholds now higher, that may no longer be the case.
“We’re seeing clients with substantial investment portfolios who assumed the age pension was simply off the table for them,” said Robert Tawil, Adviser at Vantage Wealth Management. “With these thresholds moving up, some of those same clients may now be entitled to a small part pension. The dollar amount might be modest, but it comes with a Pensioner Concession Card rather than the Commonwealth Seniors Health Card, and that card can translate into real, ongoing savings on healthcare and everyday costs. If your circumstances haven’t changed dramatically since you were last assessed, it’s worth checking again.”
What We Would Suggest
If your assets or income were previously close to these limits, now is a sensible time to revisit your position. Even a small part pension entitlement can bring valuable flexibility and concession benefits alongside it.
We’d welcome the opportunity to review your situation against the new thresholds and let you know whether they open up any entitlement for you. Please get in touch with your Vantage Wealth Management adviser to arrange a time.
*This article contains purely factual information and/or general advice and does not constitute personal financial product advice. The content of this article does not take into account your personal objectives, financial situation or needs and you must determine whether it is appropriate to your situation. We recommend you obtain financial, legal and taxation advice before making any financial investment decision.
About the Author:

Robert Tawil – Private Client Adviser – Vantage Wealth Management
Robert holds a Bachelor of Economics (Economics, Quantitative Economics, Money and Banking, and Finance) from the University of Western Australia and a Diploma of Financial Planning. This allowed him to qualify as a Certified Financial Planner®. He commenced working in the financial services industry in 2015 and is a member of the Financial Advice Association Australia.
Robert values building strong relationships that are founded on trust and is passionate about helping people take control of their financial affairs and achieve their goals.
Follow us on Social Media: